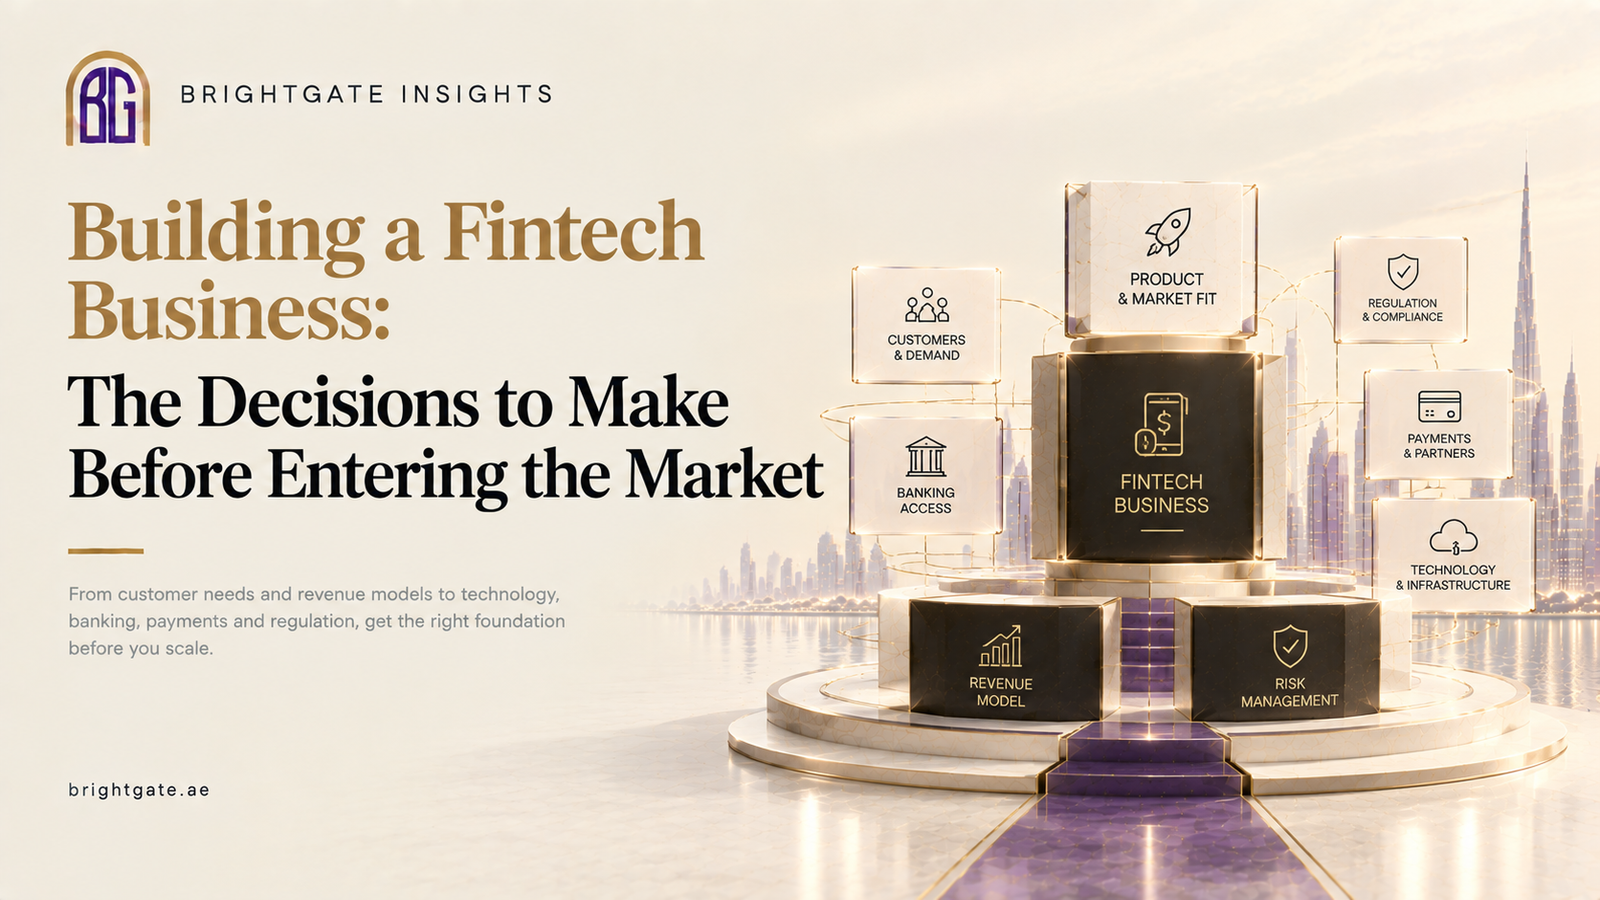
Building a fintech business starts with proving that a customer problem is worth solving. Before committing to development, founders should understand how customers address that problem today, what existing services cost and why users would switch.
The assessment should connect market demand with a viable revenue model, regulatory requirements, banking and payment relationships, technology and operational responsibilities. An attractive app cannot compensate for an impractical or commercially unsustainable operating model.
Bright Gate Group helps founders assess business structures and financial infrastructure requirements, then coordinates suitable independent specialists where required. The aim is to clarify dependencies and implementation priorities before significant resources are committed.
Understand the Rules Before Designing the Product
Regulatory requirements depend on the proposed activities, target customers, handling of customer funds and markets served. Company registration alone does not authorise regulated financial activities.
Before designing the product, founders should obtain qualified legal and regulatory advice on the proposed model. For a UAE-focused project, the assessment should identify the relevant jurisdiction and competent authority rather than assuming one regulatory route applies to every fintech business.
Create a requirements map linking product features to applicable obligations, responsible parties and evidence needed before launch. Review it whenever the product, customer segment or target market changes.
Decide How Customers Will Be Identified
Customer onboarding affects conversion, trust and financial-crime controls. Depending on the business model and applicable requirements, checks may include identity verification, business verification, beneficial ownership checks, sanctions screening and ongoing monitoring.
Digital identity tools may support document verification, biometric matching and liveness checks, but their capabilities and limitations should be assessed. Using an identity provider does not, by itself, complete every customer due-diligence obligation.
Track onboarding completion, verification times, manual-review rates and false rejections. These measures help identify friction without weakening necessary controls.
Collect information for defined purposes, protect it appropriately and establish retention policies consistent with applicable requirements. Restrict access by role and maintain records of significant changes.
Build Technology Around Reliability and Security
Technology should support expected demand while allowing routine changes to be tested and deployed safely. Clear interfaces between onboarding, payments, account records, reporting and risk controls can make integrations easier to maintain. API documentation, versioning policies and test environments should form part of provider evaluation.
Set measurable objectives for availability, response times, error rates and recovery. Targets should reflect critical customer journeys, expected volumes and the consequences of failure. A delayed dashboard and a failed payment authorisation may require different priorities; generic figures such as 99.9% availability or 300-millisecond response times should not be presented as universal standards.
Security planning should cover encryption in transit and at rest, multi-factor authentication, least-privilege access, audit logging, code reviews and tested backups. Where card data is involved, assess tokenisation and applicable payment-security requirements with qualified specialists.
Before live customer activity, define incident-response procedures, escalation contacts and recovery responsibilities. Teams should know who can restrict compromised access, preserve evidence, coordinate required notifications and authorise restoration. Test these procedures through realistic exercises.
Select Partners Without Losing Control
Fintech businesses often depend on banks, payment processors, cloud platforms, identity-verification providers and fraud-monitoring services. Evaluate providers against geographic coverage, technical compatibility, settlement arrangements, security, support availability, data handling and contractual responsibilities.
For critical dependencies, assess disruption scenarios and realistic alternatives. Establish escalation contacts, data-export arrangements, migration requirements and likely switching costs. Where immediate replacement is impractical, define how essential operations will be maintained or safely restricted.
Bright Gate Group advises on infrastructure requirements and coordinates the assessment of suitable independent providers. A responsibility matrix can clarify which tasks belong to internal teams and which belong to specialists. Provider onboarding and regulated services remain subject to the relevant institution’s assessment and approval.
Operational responsibilities should also cover complaints, refund decisions, customer communications and service changes. Clear ownership helps teams resolve issues consistently as activity increases.
Plan Payments, Reconciliation, and Cash Flow
Map the complete payment journey: initiation, processing, settlement, reconciliation, refunds and failed transactions. Identify who handles funds at each stage and which provider is responsible when something goes wrong.
Cash-flow planning should account for settlement delays, processing fees, foreign-exchange costs, refunds, disputes and any provider reserve requirements. Distinguish operating funds from customer funds where relevant, and obtain specialist advice on applicable safeguarding or segregation obligations.
For cross-border payments, assess supported currencies, intermediary institutions, cut-off times and settlement arrangements. Confirm what each payment status means: acceptance for processing does not necessarily mean funds have settled.
Monitor payment completion rates, settlement times, reconciliation exceptions and cost per completed transaction. Where relevant, also track chargebacks and refunds. Compare provider statements with internal records and assign unresolved exceptions to an owner with a defined investigation deadline.
Related Reading: Why Some Financial Businesses Scale Globally While Others Struggle
Test Demand Before Expanding
Use a controlled pilot to test the customer journey and operating model once the necessary permissions and provider arrangements are in place. Where live activity is not yet permitted, use prototypes or sandbox testing without assuming that testing removes regulatory obligations.
Define what the pilot must demonstrate, such as onboarding completion, successful transactions, repeat usage, support demand and manageable fraud losses. Set criteria for proceeding, revising the product or pausing the pilot, including escalation and stop conditions.
Measure meaningful customer activity rather than registrations alone. Review retention, repeat transactions, customer acquisition costs and contribution margin alongside complaints and support tickets. Use the findings to prioritise specific improvements.
Choose the initial market based on customer demand, operating costs, provider availability and applicable requirements. Expansion into another country should trigger a fresh assessment of licensing, payments, data handling, customer disclosures and support capabilities.
Turn Preparation Into a Practical Advantage
A fintech business is not ready to launch simply because its app is complete. Founders also need a tested customer proposition, a credible revenue model, appropriate permissions, dependable infrastructure and clear operational responsibilities.
Before launch, confirm that the business can onboard its intended customers, process and reconcile transactions, handle complaints and respond to disruption. Unresolved dependencies should have an owner and a practical resolution plan.
Bright Gate Group helps founders assess business structures, financial infrastructure and implementation priorities, then coordinates suitable independent specialists. Explore our Financial Business Setup Advisory framework or contact the team to discuss your proposed fintech model and launch requirements.